Forex traders love a good legend, and Andy Krieger's 1987 trade against the New Zealand dollar is one of the field's favorites. It gets retold as a David-versus-Goliath story: one trader, one small currency, one enormous payday.
That version isn't wrong, exactly, but it skips the part that actually matters. Krieger didn't win because he had more money than everyone else. He won because he asked a different question than everyone else was asking. That question is worth unpacking, because it still applies to markets today.
From Sanskrit Studies to the Trading Floor
Krieger's path into finance was unusual. He studied philosophy and South Asian studies at the University of Pennsylvania, with graduate-level work in Sanskrit, before earning an MBA at Wharton. He started his career at Salomon Brothers and moved to Bankers Trust in 1986, where he became known as one of the bank's top currency options traders.
It's a useful reminder that the skill behind a great trade isn't always a finance degree. What Krieger brought to the job was closer to close reading: the habit of asking whether a price actually meant what everyone assumed it meant.
A Trading Limit Unlike Anyone Else's
Bankers Trust reportedly gave Krieger a trading limit of around $700 million — compared with roughly $50 million typically given to other traders at the time. That gap wasn't just about capital. It reflected how much the firm trusted his judgment with real risk on the line.
That limit is also the reason the New Zealand dollar trade was even possible a year later.
What Black Monday Changed
On October 19, 1987, the Dow Jones Industrial Average fell about 22.6% in a single session — the event now known as Black Monday. Panic spread through global markets, and investors scrambled out of U.S. dollar assets into anything that looked safer.
A number of currencies strengthened against the dollar in the chaos that followed. Most traders read that as a simple signal: buy the currencies going up. Krieger read it differently.
Was a currency actually becoming more valuable, or was it just becoming more expensive?
Those aren't the same question. A currency can rise because investors are genuinely fleeing risk, or it can rise because a wave of panic-driven buying has pushed its price past what its underlying economy supports. Krieger was betting on the second explanation for one specific currency: the New Zealand dollar.
Why the New Zealand Dollar, Specifically
This is the detail most retellings skip, and it's the one that makes the trade interesting rather than just lucky.
The New Zealand dollar wasn't a heavily traded currency like the U.S. dollar or the yen. Its market was thin — meaning relatively few buyers and sellers, and relatively shallow liquidity.
Thin markets behave differently under pressure. Picture the difference between shouting in a crowded stadium and shouting in a small room: the same volume produces a very different effect depending on how many people are around to absorb it. In a currency market, a large sell order dropped into a thin market moves the price far more than the same order would in a deep one.
So Krieger wasn't simply betting that the New Zealand dollar was overvalued. He was looking for a currency that was both overvalued and structurally vulnerable to a large, sudden move — a combination that's much rarer than overvaluation alone.
The Real Tool Was Options, Not Cash
Here's where the story usually gets oversimplified. Krieger didn't sell $700 million worth of New Zealand dollars in the spot market. He built his position largely through currency options, a derivative that lets a trader gain exposure to a much larger notional amount than the actual cash outlay requires.
That distinction matters for understanding what actually happened:

You'll often see claims that Krieger "sold more New Zealand dollars than existed." That framing confuses notional exposure with physical currency. What he actually did was use derivatives to construct a position with outsized notional exposure relative to his capital — a very different (and more accurate) description. Some sources cite leverage figures as high as 400-to-1, but that number varies by source and shouldn't be treated as confirmed fact.
Why the Price Actually Moved
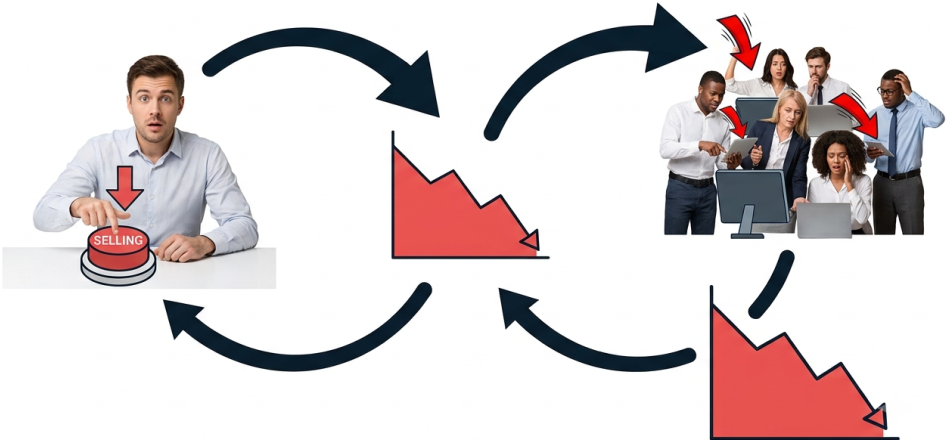
A large trade doesn't just reflect information — it can create information for everyone watching it.
When other market participants saw aggressive selling of that size, many concluded there had to be a reason behind it. Some followed suit and sold too, which pushed the price down further, which encouraged more selling. This kind of chain reaction is a textbook case of herding behavior combined with positive feedback: price movement in one direction attracts more of the same movement, at least for a while.
That's an important nuance. The trade's impact wasn't purely a function of Krieger's capital — it was also a function of how other traders interpreted and responded to it.
No, He Didn't "Break" a Central Bank
You'll frequently see this trade described as Krieger "breaking" New Zealand's central bank. That phrase is more dramatic than accurate. He put significant downward pressure on the currency and contributed to a sharp move — but the Reserve Bank of New Zealand didn't collapse as an institution.
Central banks aren't powerless in these situations, but they aren't omnipotent either. They can use interest rate policy, foreign exchange reserves, and direct market intervention — yet none of those tools guarantee they can force a market back to where policymakers want it. The more accurate framing is that Krieger's trade contributed to a currency shock, not an institutional collapse.
The Trade Could Have Gone the Other Way
It's easy to admire a winning trade and forget how much risk sat behind it. If the New Zealand dollar had kept climbing instead of falling, a highly leveraged position of that size could have produced losses just as extreme as the gains.
That's the nature of leverage — it amplifies outcomes in both directions, not just the favorable one. The lesson from Krieger's trade isn't "bet big when you're confident." It's closer to the opposite: the larger the position you're able to take, the more precisely you need to understand your downside before you take it.
$300 Million in Profit, $3 Million in Pay
Bankers Trust is estimated to have made roughly $300 million on the trade — the number most often cited in retellings. A less-discussed figure is what Krieger himself reportedly earned that year: around $3 million in salary and bonus.
That gap says something worth remembering, for traders and employees generally: the size of the value you create and the size of the reward you personally receive aren't the same equation. One is a market outcome; the other is decided by whoever controls the compensation structure. Krieger left Bankers Trust in 1988 and went on to work at George Soros's Quantum Fund.
What This Trade Actually Teaches Individual Investors
The takeaway isn't "use massive leverage" — most individual investors shouldn't, and the risk profile of a $700 million institutional trading limit has nothing to do with a personal portfolio. The more useful lesson is the set of questions Krieger was asking before he ever placed the trade.

The same framework applies well beyond currencies. Before buying a stock, it's worth asking not just "is this a good company?" but "how much of that good news is already reflected in the price?" The same goes for a fast-rising crypto asset: the question isn't just why it's climbing, but whether the expected future is already baked into today's valuation.
The Real Skill Wasn't Boldness
Strip away the drama, and Krieger's edge wasn't a willingness to take a bigger risk than anyone else. It was a willingness to question a price that everyone else had already accepted as reasonable.
In October 1987, most market participants were reacting to fear. Krieger was asking whether the market's fear-driven pricing actually made sense. That question — is the current price a reflection of reality, or just a reflection of what everyone currently believes — is one that still holds up for any market, in any decade.
This article is for informational purposes only and does not constitute investment advice. Any trading decisions and their outcomes are the sole responsibility of the individual investor.


